Mechanics of BJF Trading & PZ Arbitrage EA Review: Latency Software Comparison
The operational framework of bjf arbitrage revolves around price dissemination delays across fragmented liquidity venues. In modern decentralized OTC markets-particularly Foreign Exchange and CFDs-prices do not originate simultaneously at every trading venue. Tier-1 bank liquidity pools, primary ECNs (such as LMAX, EBS, and Currenex), and regulated futures exchanges update their quotes several milliseconds ahead of secondary retail brokers.
When high-speed software observes a price impulse on a primary institutional feed, a predictable price gap emerges on slower retail terminals. Strategies targeting forex statistical arbitrage monitor this price discrepancy tick-by-tick. If the measured divergence exceeds the prevailing bid-ask spread plus expected commissions and execution slippage, the system fires an instantaneous order to capitalize on the stale quote before the broker's liquidity bridge adjusts.
Overcoming Broker Virtual Dealers & Latency Buffers
Implementing pz arbitrage ea requires understanding broker risk routing. When retail brokers operate on a B-book model, fast profitable latency flow represents a direct balance sheet cost. Consequently, dealing desk systems install latency monitoring utilities (such as virtual dealer plugins) that detect orders holding positions for under 2 seconds or entering on fast ticks.
Brokers counter arbitrageurs through asymmetric slippage: profitable orders arriving during fast price movements are delayed by 100ms to 300ms until the quote catches up, resulting in negative fills, while unprofitable orders are filled instantly. Successful traders counter this by trading on genuine A-book ECN bridges, configuring strict maximum deviation tolerances, and referencing arbitrage in forex market to verify low-latency broker suitability.
Reddit & Forex Factory Practical Findings
Trader Community Discussions: Forex Factory & Reddit r/Forex
Independent discussions across Forex Factory and r/Forex reveal several practical realities regarding latency arbitrage and expert advisors:
- The 'Free EA' Trap: Forum members frequently warn against free latency arbitrage EAs downloaded from unknown websites. These files either contain malicious DLL trojans that steal account credentials, or rely on public price feeds that are slower than the retail broker itself.
- Fast Data Feed Requirement: A profitable latency arbitrage setup requires a legitimate high-speed data stream (such as Rithmic, CQG, LMAX, or Binance WebSocket) running on a server physically adjacent to the broker's bridge in London (LD4) or New York (NY4).
- Profit Retention: Traders report that attempting latency arbitrage on heavily B-booked brokers inevitably results in trade cancellations under 'market abuse' terms of service. Sustainable results require A-book institutional routing.
Technical Specifications & Comparative Matrix
Quantitative benchmarks defining operational parameters for bjf arbitrage across industry venues and architectures:
| Arbitrage Methodology | Price Feed Speed | Holding Duration | Broker Detection Risk |
|---|---|---|---|
| Two-Leg Latency Arbitrage | Institutional ECN / FIX API (< 1 ms) | 200 ms - 3 seconds | High on B-Book; Neutral on Prime DMA |
| Triangular Currency Arbitrage | Multi-Pair Cross Matrix (< 2 ms) | 500 ms - 15 seconds | Low (Market Neutral Mathematical Arbitrage) |
| Statistical Mean-Reversion Arbitrage | Tick-by-Tick Cointegration Feed | 2 seconds - 5 minutes | Very Low (Standard Quantitative Flow) |
| Reverse / Lock Latency Hedging | Dual Fast/Slow Broker Bridges | Variable (Position Open Across Accounts) | Moderate (Requires Dual-Broker Coordination) |
Implementation Protocol & Risk Control
Deploying automated execution for bjf arbitrage requires a disciplined four-stage operational workflow:
1. Infrastructure & Colocation Setup
Establish your server inside the primary financial data center (Equinix LD4 or NY4) matching your broker's trade execution server. Audit ping stability to eliminate packet jitter.
2. Fast Market Data Calibration
Integrate a verified institutional fast price feed (such as LMAX or Rithmic). Ensure tick timestamp synchronization matches UTC atomic clock standards with microsecond precision.
3. Gateway & Bridge Optimization
Deploy native C++ DLL memory hooks or direct FIX 4.4 API order gateways. Configure hard slippage ceilings and spread filters to reject fills during illiquid spread widening.
4. Post-Trade Mark-Out Telemetry
Log every trade execution round-trip. Measure mark-out profitability at 100ms, 1 second, and 5 seconds post-fill to verify that your broker provides genuine A-book execution.
Westernpips Private 7: Low-Latency Precision Engine
Westernpips has pioneered latency arbitrage and high-frequency trading technology since 2007. Private 7 connects to ultra-fast feeds and executes orders via FIX API and low-level bridges with sub-millisecond accuracy.
Explore Westernpips Private 7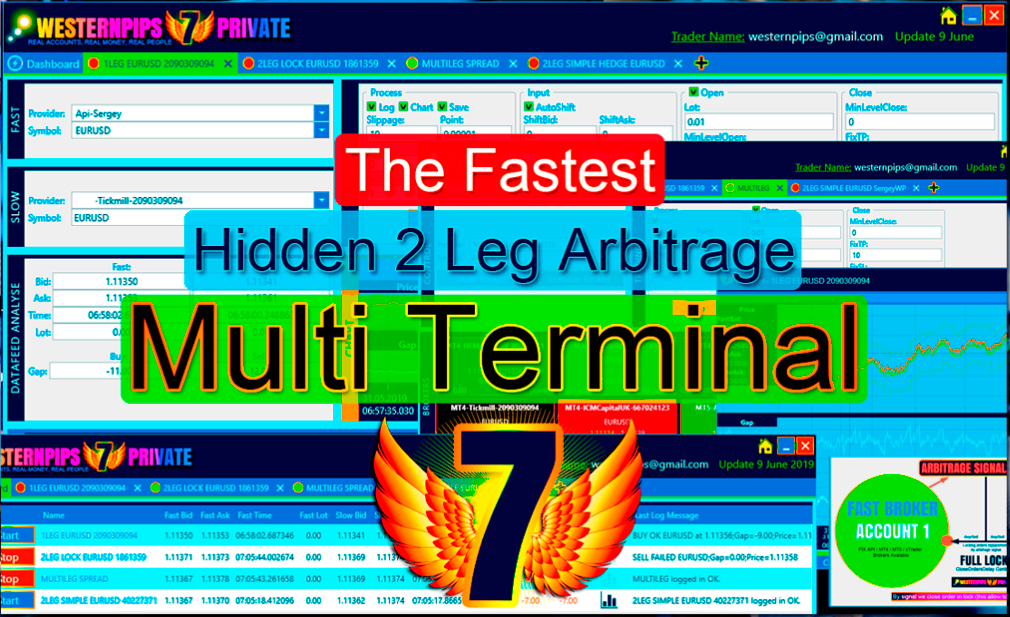
Frequently Asked Questions
Why is a fast institutional feed necessary for bjf arbitrage?
The entire premise of latency arbitrage relies on detecting a future price change before it appears on the target broker. Without an institutional ultra-fast feed (like LMAX or Rithmic), the system cannot generate an accurate forward signal.
Is bjf arbitrage legal in foreign exchange trading?
Yes, latency arbitrage is completely legal under commercial law. However, individual retail brokers may prohibit latency-based strategies in their client agreement, particularly if operating a B-book execution model where the broker absorbs client profits.
How does Westernpips Private 7 handle execution slippage?
Westernpips Private 7 incorporates millisecond execution telemetry, dynamic slippage limits, and spread filters that automatically abort order submission if the broker's bridge latency or spread widens beyond profitable thresholds.
Related Knowledge Base & Guides
Expand your research into related execution mechanics, algorithmic frameworks, and broker policies: